Investing
Sequence risk: why the first ten years of retirement decide
Two retirees, the same average return and very different outcomes. How the order of returns can break a plan and what early retirees can do about it.
The withdrawal rate is the share of your savings you spend in year one. A bad first few years can matter more than the average return.
Taking CHF 40’000 / year a year, steady returns would keep your savings growing. After a bad start (two years at −20 %), they last about Over 100 years.
Use this in your full plan →Estimates for planning, not advice. Use at your own risk. Read the full disclaimer
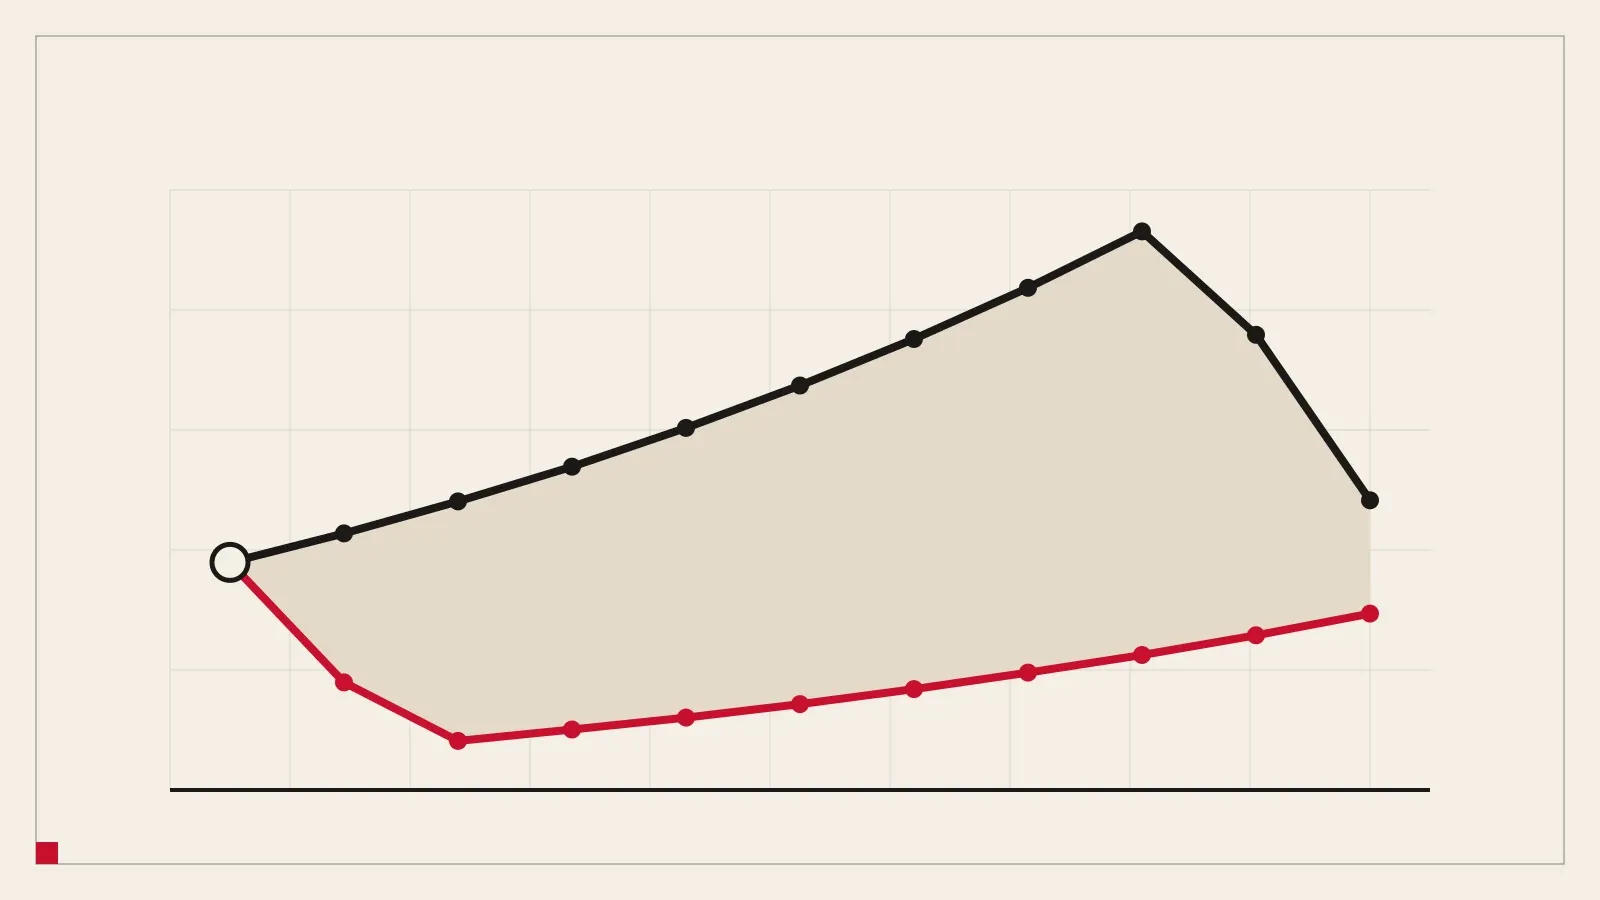
Each year you take the same amount, in today’s francs, then the rest earns the real return. The tool counts the years until the money runs out:
The gap between the two lines is sequence-of-returns risk. For why we suggest 3.5 % for long early retirements, see the 4 % rule.
Context
Real index returns, before inflation and fund costs. Our default for stocks is 8.0% a year; the last two decades were stronger, and they included a 67 % fall in francs.
| Index | Period | Currency | Per year |
|---|---|---|---|
| S&P 500with dividends | 2006–2025 | USD | 10.9% |
| MSCI Worldwithout dividends (add about 2 %) | Oct 2016–Sep 2026 | CHF | 9.4% |
| Swiss equitieswith dividends | 2009–2025 | CHF | 8.5% |
Past returns do not predict future returns. Sources: chartrow.com, msci.com, pictet.com. Try these returns in the calculator →
The 4 % rule comes from US data over 30-year retirements. Early retirees need 40 years or more, so 3 to 3.5 % gives more margin. Read our article on the 4 % rule.
Two years of −20 % right after you stop, followed by catch-up years with the same 10-year average. It shows sequence risk: losses early in retirement hurt most because you sell low to live.
Yes. Everything is in today’s francs, so the yearly amount keeps its buying power.
Investing
Two retirees, the same average return and very different outcomes. How the order of returns can break a plan and what early retirees can do about it.
The numbers
The 4% rule comes from US data over 30 years. Early retirees need longer horizons, so 3.5% is the safer start. What the rule says and what it does not.
Last reviewed: